
The Defense Credit Union Council just sent the FDIC a polite but firm message: we need to talk about your proposed merger rule.
Specifically, the part where credit unions get singled out for different treatment when they want to buy a bank.
Here’s the thing—DCUC isn’t throwing a fit about merger reform as a whole. They’re fine with regulators taking a harder look at financial strength, service continuity, and community impact. What they’re not fine with is a rule that treats credit union buyers differently than everyone else in the room.
Why Credit Unions Are Speaking Up
“Credit unions are not-for-profit, member-owned cooperatives. That structure is central to our position on bank acquisitions,” explains Anthony Hernandez, DCUC President and CEO (and retired U.S. Air Force Colonel). “Our objection concerns the separate treatment of credit union buyers, not the requirement to examine financial strength, service continuity and community needs.”
The FDIC Board greenlit this proposal on September 17, 2026, and published it five days later. The agency’s stated goal sounds reasonable enough: make merger reviews faster and more predictable. But—and this is a big but—it’s still just a proposal, not a done deal.
The Service-Review Problem
Buried in the proposal is section 333.5(e)(2)(ii), which specifically calls out potential reductions in products and services when a credit union buys a bank. The FDIC’s explanation suggests these reductions would count against the transaction. Sure, the broader framework looks at service changes in all mergers, and this isn’t an automatic “no.” But why does it need its own special provision just for credit unions?
DCUC wants that provision replaced with a standard that looks at material community effects across all transactions, regardless of who’s buying. This assessment would consider practical questions like: Who actually uses the affected service? What alternatives exist? Can people afford them? What’s the transition plan? What are the deal’s overall benefits and risks?
And just to be clear—DCUC isn’t asking for a free pass. They’re not seeking automatic approval or an exemption from consumer protections. They just want a level playing field.
The Competition Math Doesn’t Add Up
There’s also a wonky issue with how the proposal calculates market share for credit unions with branches both inside and outside a given market. The current approach divides shares equally among all branches, which doesn’t necessarily reflect reality.
DCUC wants room for actual evidence about where members live and which branches they can realistically access. They’re also asking for clarity on how NCUA approvals and supervisory findings would factor into FDIC reviews—without stepping on either agency’s toes.
Let’s Talk About the Bank Sellers
It’s worth remembering that when a credit union “buys” a bank, they’re not actually purchasing the bank charter. The NCUA describes these as voluntary, regulated purchases of assets and assumptions of liabilities. All the normal approvals still apply, including membership eligibility requirements, financial capacity checks, and account insurance arrangements.
The Irony Isn’t Lost on Anyone
“There is an irony here,” notes Jason Stverak, DCUC Chief Advocacy Officer. “Credit union advocates are defending a bank’s ability to consider the best qualified offer, including a credit union offer, while ICBA is campaigning against that option.”
Stverak points out that DCUC has highlighted how ICBA’s membership-dues structure might explain their opposition. After all, when a bank becomes a credit union, it’s no longer paying dues to the banking trade group. “Protecting an association’s dues base is not the same as representing a bank that has decided a credit union offer merits consideration,” he adds.
Not all banking groups are singing the same tune, though. The American Bankers Association actually welcomed the September proposal, citing modernization of competition guidelines. DCUC’s beef is with specific provisions targeting credit unions, not with the idea of streamlining merger reviews.
It’s About Real People, Not Paperwork
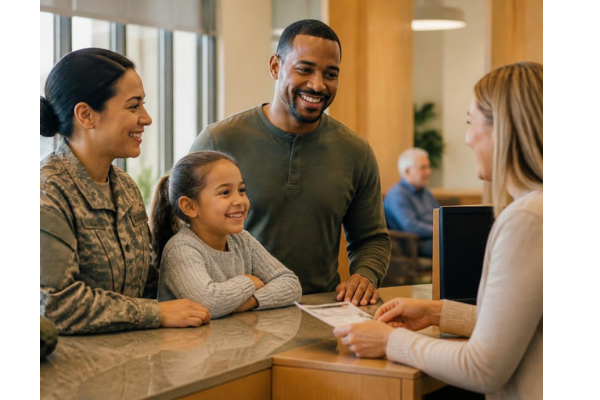
“Families do not experience a merger as a regulatory filing. They experience it when they deposit a paycheck, seek a loan or ask for help,” Hernandez says. “For DCUC, member ownership and the actual services available after closing are central to understanding a transaction’s impact. That includes servicemembers, veterans and families managing finances through a deployment or relocation.”
And that’s really the heart of it. Regulatory filings matter, sure. But what matters more is what happens after the ink dries—when real people walk into a branch or log into their accounts.
What Happens Next
The proposal doesn’t ban credit unions from buying banks or impose some kind of exit fee (despite what you might hear in certain circles). Comments on RIN 3064-AG18 are due November 23, 2026, and DCUC plans to stay on top of the rulemaking process, keeping its Military Advocacy Committee and credit union leaders in the loop about any developments that matter.
Translation: This conversation is far from over.