
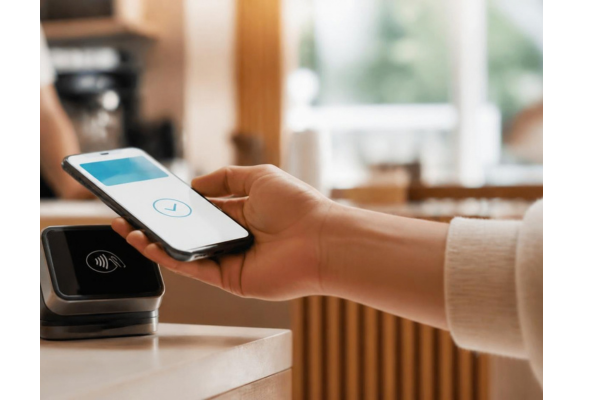
Here’s a problem you might not have thought about: you get a shiny new debit card in the mail, but before you can tap your phone to pay for coffee, you’ve got to manually hunt down your digital wallet app, type in all those card numbers, and hope you didn’t fat-finger anything.
It’s 2025—shouldn’t this be easier?
Good news: it’s about to be. CPI (Nasdaq: PMTS), a payments tech company that handles both physical cards and digital payment solutions, just announced they’re teaming up with Bankjoy to bring something called “push provisioning” to community banks and credit unions. Translation? Your bank can now load your card directly into Apple Pay, Google Pay, or Samsung Pay for you. No typing, no hassle, just instant access.
Why This Actually Matters
Think of push provisioning as the difference between assembling IKEA furniture yourself versus having someone do it for you. When your financial institution can push your card info straight to your digital wallet, you’re ready to pay immediately—no manual entry required. This is especially clutch when you’re getting a replacement card and don’t want to deal with the payment limbo that usually follows.
And people actually want this. A 2025 CPI consumer survey found that 71% of respondents between 18 and 37 years old think it’s appealing when their bank adds new payment info to their digital wallet automatically. Makes sense—convenience tends to be popular.
For banks and credit unions, the benefits go beyond happy customers. CPI’s data shows that financial institutions using push provisioning see activation rates jump by 15-20%. That’s not nothing.
The Real Competitive Edge
Rob Dixon, Chief Digital Officer at CPI, put it perfectly: “When a customer reaches for a phone to pay, the cards already in the preferred digital wallet have an advantage. Working with CPI gives Bankjoy community banks and credit unions a better opportunity to earn that everyday use from the start.”
In other words, if your card is already sitting in someone’s digital wallet, you’re the one they’re using at checkout. First-mover advantage, payment edition.
No Tech Headaches Required
Here’s where it gets interesting for the financial institutions themselves. Setting up integrations with multiple digital wallets, card networks, and payment processors sounds like the kind of project that requires a massive IT team and a bigger budget. CPI handles all of that backend complexity—the integrations, the ongoing maintenance, the updates needed to keep everything playing nice with Apple, Google, and Samsung.
Community banks and credit unions get enterprise-level capabilities without enterprise-level headaches or costs. They can focus on their customers while CPI deals with the technical plumbing that makes it all work.
“Push provisioning is quickly becoming a baseline expectation for cardholders, and community financial institutions need a partner who can deliver it without enterprise-level complexity or cost,” said Weiwei Duncan, co-founder and Chief Operating Officer of Bankjoy. “CPI brings the processor integrations, wallet relationships, and implementation expertise to make this a reality for our clients.”
The partnership means Bankjoy’s clients—community banks and credit unions that might not have the resources of a Chase or Bank of America—can now offer the same seamless digital wallet experience that customers have come to expect from the big players. And in a world where paying with your phone is increasingly the norm rather than the exception, that levels the playing field in a meaningful way.