
By Jason Stverak, Chief Advocacy Officer, Defense Credit Union Council
Washington is consumed by the next election. Who wins the House? Who controls the Senate? What does the map look like the morning after?
Here is another question worth asking: What will the people already elected to Congress accomplish before their terms end?
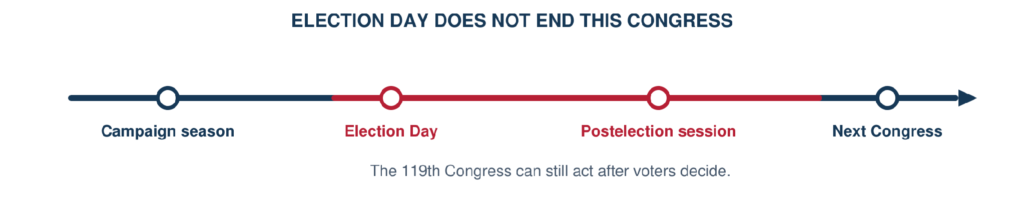
The 119th Congress still has work to do. Regardless of what happens on Election Day, lawmakers will return to Washington with the authority to legislate and the responsibility to deliver. The Senate’s calendar already anticipates work after the election.
Some lawmakers will return celebrating. Others will return disappointed. Neither outcome changes what a veteran business owner needs from Washington.
Families will still face bills, businesses will still need financing, and credit unions will still be answering the phone. Congress must bring that same commitment to its remaining legislative days.
For credit unions and the communities they serve, that remaining time matters. A veteran trying to open a business cannot pay a supplier with a campaign promise. A military family working through its finances cannot deposit a press release. They need Congress to turn support into law.
The Defense Credit Union Council is putting specific proposals before lawmakers, such September 8 letter to congressional leadership that urged a negotiated financial services section in the defense authorization bill, including permanent Central Liquidity Facility enhancements, modernized loan maturity authority, and the Veterans Member Business Loan Act. Congress has a clear place to start.
Take the Central Liquidity Facility, or CLF, which helps credit unions obtain emergency liquidity so they can continue serving members during financial disruption. DCUC has repeatedly urged Congress to make access more dependable, including through the bipartisan Padilla-Cramer legislation.
The reform would let a corporate credit union arrange participation for a subset of the credit unions it serves, making access more workable for smaller institutions. Financial preparedness requires certainty. Repeatedly revisiting temporary authority leaves institutions planning around Washington’s calendar when they should be planning around members’ needs. Waiting until financial stress arrives is a lousy strategy for building a safety net.
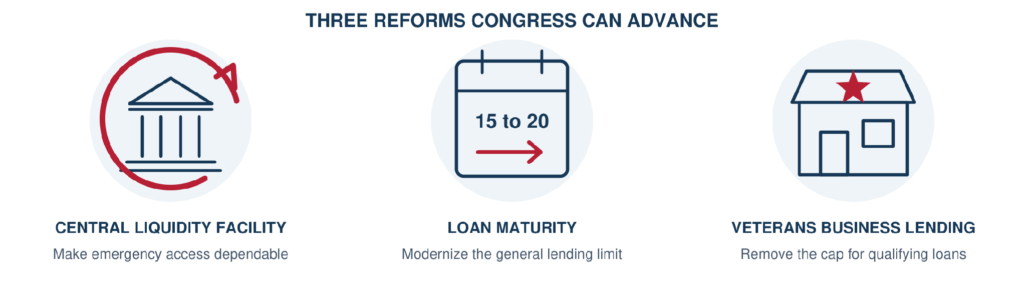
Then there is loan maturity reform. The Expanding Access to Lending Options Act would modernize the general federal credit union loan maturity limit from 15 years to 20 years, with authority for the National Credit Union Administration to permit longer terms. Existing exceptions already allow longer maturities for certain loans.
That distinction matters, but so does the larger point: federal law should give credit unions reasonable flexibility to structure responsible financing around a borrower’s circumstances. Military families relocate. Housing plans change. A servicemember may want to purchase a future retirement home while stationed somewhere else. Lending rules should account for those realities.
Longer terms can reduce monthly payments, although they can also increase total interest costs. Borrowers deserve clear disclosures, careful underwriting, and meaningful choices. Congress can expand those choices while preserving oversight. Leaving an outdated general limit untouched accomplishes nothing for the family trying to make its budget work.
And Congress should finally pass the Veterans Member Business Loan Act.
Federal law generally limits a credit union’s member business lending to 12.25 percent of its assets, subject to exceptions. This legislation would exclude qualifying veteran business loans from that restriction. DCUC and The American Legion have jointly urged its passage.
Think about what that means. A veteran brings a credible business plan to a credit union prepared to evaluate it. An institution-wide ceiling should not close the conversation before the merits of that loan can decide it.
The bill would preserve underwriting and supervisory requirements. Veterans would still have to qualify. Credit unions would still bear responsibility for their decisions. Congress would remove a barrier to responsible lending without creating another federal financing program.
Lawmakers who say they support veterans have an opportunity to put something useful behind those words. Help a veteran purchase equipment, acquire a business, or hire that first employee. Give service an opportunity to become ownership.
When government shutdowns threaten family finances, defense credit unions step forward with emergency loans, payment relief, and counseling. Congress should strengthen that capacity. The people who sustain our national defense deserve financial institutions equipped to keep serving.
Getting these reforms enacted will require choices. Committee leaders should resolve differences now. Congressional leadership should identify a workable legislative path and make room for votes. DCUC has proposed the defense authorization bill as one opportunity, through a focused bipartisan agreement that supports military financial readiness. Congress should pursue that route where agreement permits and keep other viable paths open.
That means doing the unglamorous work that gets legislation across the finish line: settling technical questions, negotiating workable language, and securing the votes. Start those conversations before the election. Keep staff engaged afterward. Every unresolved detail handed to the next Congress becomes another reason members must keep waiting for relief.
Those negotiations also must protect credit unions’ ability to serve. DCUC has urged Congress to preserve our tax status, grounded in our structure as member-owned, not-for-profit cooperatives. Year-end bargaining should respect that foundation.
Credit union leaders have a role here, too. Ask your representatives what they will help enact before this Congress ends. Bring them a member’s story. Explain the obstacle and the solution. Then follow up. A supportive meeting is a beginning. Members deserve the result.
If your party wins in November, come back ready to work. If your party loses, come back ready to work. If you are retiring or leaving office, you still have an opportunity to leave something valuable behind.
The oath carries no election-season exception. Neither should the effort.
Congress can finish this race with meaningful progress for credit unions, military families, and veterans. The proposals are there. The need is real. The time remaining deserves to be used.
Be bold, Congress. Finish strong.