
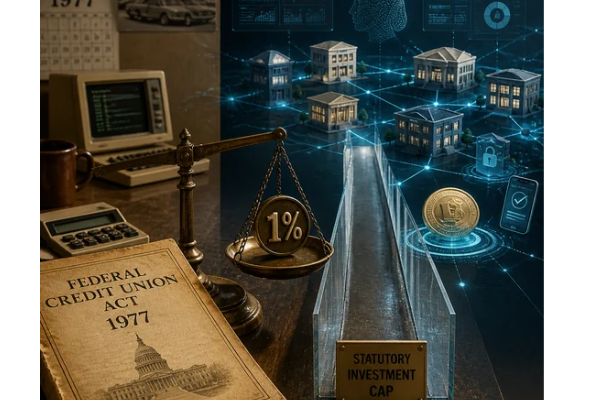
Congress picked the 1% limit on credit union investments in CUSOs back in 1977, and nothing in the legislative history explains why.
Not a word about the number. Nearly 50 years later, it still governs how federal credit unions back the very organizations meant to help them compete.
NACUSO is pushing to change that. Here’s the case, and why credit unions should add their voices.
Why CUSOs matter
Credit union service organizations (CUSOs) are the cooperative idea put to work. Credit unions pool money, expertise, and risk, and end up with scale none could build alone. The biggest ones now serve thousands of institutions: Origence in indirect lending, Velera in technology and payment processing, and MBFS in commercial and member business lending.
The rules for investing in them, though, belong to a different era.
How the cap works
A federal credit union can invest in CUSOs, but only up to 1% of its paid-in and unimpaired capital and surplus (roughly, shares plus undivided earnings). Key points:
- One shared limit. Every CUSO investment counts toward the same 1%, whether it’s lending, mortgage services, insurance, or technology.
- Strength doesn’t matter. Hit the cap and you’re done, however healthy your balance sheet or promising the opportunity.
- It’s written into law. The cap lives in the Federal Credit Union Act, not NCUA regulation, so changing it takes an act of Congress.
- Loans are separate, but different. A distinct 1% limit covers loans to CUSOs. A loan isn’t an ownership stake, though, and it doesn’t buy a seat at the table.
- Charter matters. State-chartered credit unions follow state law, and many states allow higher limits. Federal credit unions are left at a disadvantage.
There’s a cruel twist here. As former NCUA Chairman Dennis Dollar has noted, the most collaborative credit unions, the ones already invested in several CUSOs, have the least room left for the AI and fintech CUSOs they need next.
A number with no backstory
Think about what 1977 looked like: no internet, no smartphones, no mobile apps, no cloud, no AI, no crypto. All of that arrived since, and the cap didn’t budge. NACUSO General Counsel Brian Lauer told CU Today that the legislative record never discusses why 1% was chosen. It’s arbitrary, plain and simple.
The innovation gap
The timing makes this worse. AI, stablecoins, and digital payments offer credit unions ways to improve lending, catch fraud, trim operations, and serve members better. All of it takes capital. Banks and fintechs are spending billions, and credit unions need to invest alongside them and help shape the tools. Dollar says the cap leaves credit unions “behind the AI and fintech eight ball.” NACUSO would argue they’re already there.
Stablecoins show how this plays out. Under the GENIUS Act, federally insured credit unions can’t issue payment stablecoins directly. NCUA’s proposal would require issuance through a separately organized subsidiary or a CUSO approved as a licensed issuer. A credit union already invested in insurance, business lending, or back-office CUSOs could burn through its remaining room just setting one up.
Smaller credit unions feel this most. They have thinner infrastructure and fewer resources, and CUSOs are how they level the field by sharing costs and spreading risk. Limit their ability to invest, and the whole movement slows.
What a fix looks like
A flat 1% ignores the differences between institutions. Better rules would reflect each credit union’s financial condition and strategy. Two paths are on the table:
- Raise it. Dollar suggests that if Congress keeps a statutory cap, something near 10% would make sense.
- Drop it. Remove the number from the law, let each credit union set its own CUSO investment policy, and let federal and state regulators judge safety and soundness through exams and supervision.
The right level depends on capital, balance sheet, and risk management. For some, even 10% could be too little. For others, 1% might be too much.
None of this means loosening discipline. NACUSO wants updated rules, not reckless investing. Governance and due diligence stay; the arbitrary ceiling goes.
Where things stand
NACUSO is working with America’s Credit Unions and has hired a Washington advocacy firm to coordinate Capitol Hill outreach. The issue gained traction during last year’s stablecoin legislation talks, and state leagues and credit union leaders have been generous collaborators.
Congressional response has been encouraging. Many offices don’t fully understand what CUSOs are, but once the issue is explained, NACUSO hasn’t heard a single argument that a higher cap would hurt credit unions, the industry, or members. Staff have shown real energy, and recognition is growing that 1% is arbitrary and overdue for review.
The goal is a clean fix, not a larger package that piles new regulatory burdens onto credit unions. For once, the industry gets to play a bit of offense in Washington.
What you can do
Technology isn’t waiting, and credit unions shouldn’t be held back by a limit nobody can justify. Contact NACUSO to learn how to help, talk to your legislators, and make your voice heard.
The cooperative model only stays a competitive advantage if credit unions are allowed to invest in it.