
A good product doesn’t sell itself to every kind of lender.
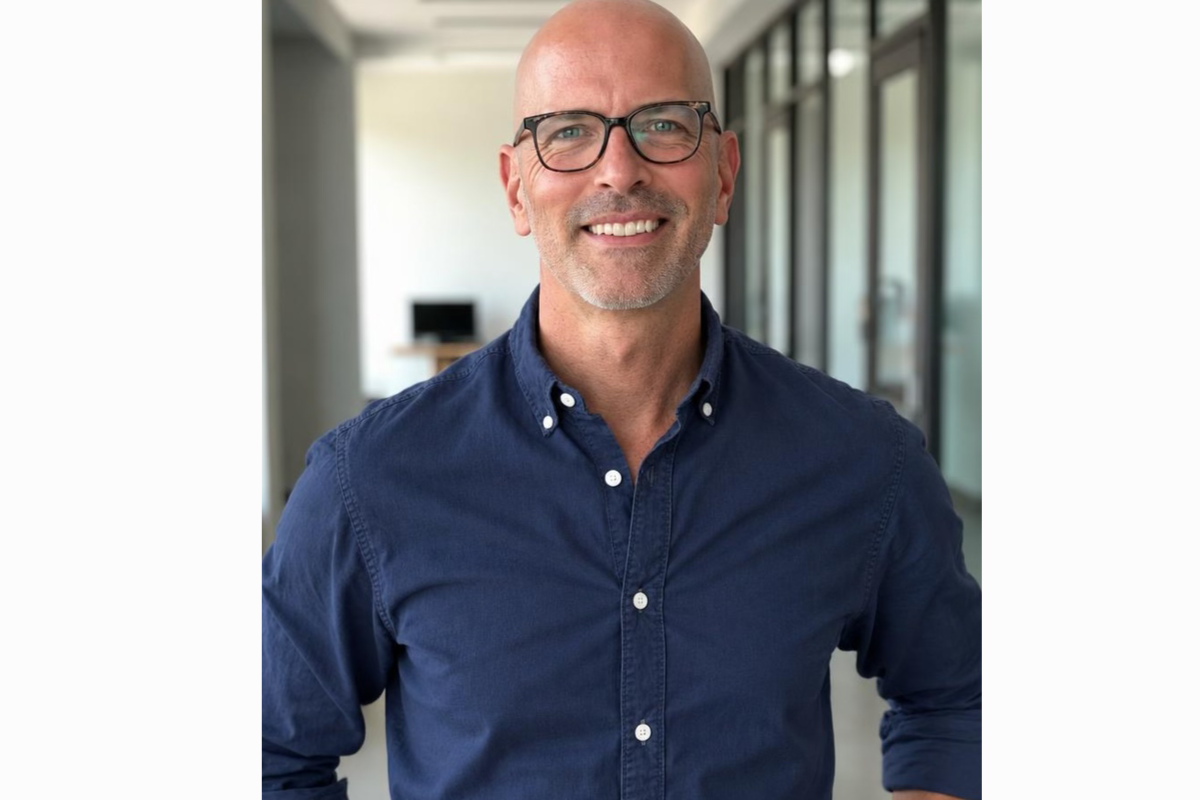
Banks, credit unions, and nonbank lenders each have their own risk questions, and a cashflow bureau that wants to serve all of them needs people who understand the differences. That’s the job EDGE just handed to Eric Werab, who joins as Chief Revenue Officer.
EDGE is a cashflow bureau and consumer reporting agency built by lenders for lenders. Werab will lead an expanded commercial and customer-facing team, with dedicated coverage for banks, credit unions, nonbank lenders, and other businesses that assess consumer risk. In plain terms, EDGE is building specialized sales and service teams so each type of customer gets solutions fitted to its needs rather than a one-size-fits-all pitch.
“We’ve built a strong foundation serving dozens of lenders and, under Eric’s leadership, will extend our capabilities to a broader range of financial institutions and other businesses that assess consumer risk,” said Brian Reshefsky, CEO of EDGE. He described Werab as someone who has spent his career helping lenders solve complex problems with data and technology, building teams that connect new products to real business needs. Werab will now build the hands-on teams that make that happen at EDGE.
Werab brings more than 20 years of experience commercializing and growing financial technology businesses. Most recently he was Senior Vice President of Americas Sales at GBG, a global identity and fraud company. Before that, he held commercial leadership roles at NeuroID, Prove, Point Predictive, and Fiserv, a résumé that covers both growth-stage startups and established financial services providers. The common thread is selling solutions to banks, credit unions, and other lenders.
Werab sees timing on his side. “EDGE has built a differentiated cashflow bureau grounded in successful lending experience, with capabilities that address the full consumer credit lifecycle,” he said. He added that cashflow intelligence is playing a bigger role alongside traditional bureau data in how lenders evaluate risk and manage credit, and that EDGE has the technology, analytics, and firsthand lending expertise to lead that shift. “I’m excited to expand the EDGE network and help more institutions put those capabilities to work.”
For lenders, the practical upshot is simple. If you’ve been weighing cashflow data as a complement to traditional credit reports, EDGE is signaling that it wants to work with institutions of all types, and that you can expect a team built around your segment, not a generic sales process. It’s a good moment to ask how cashflow signals could sharpen your own risk decisions.