
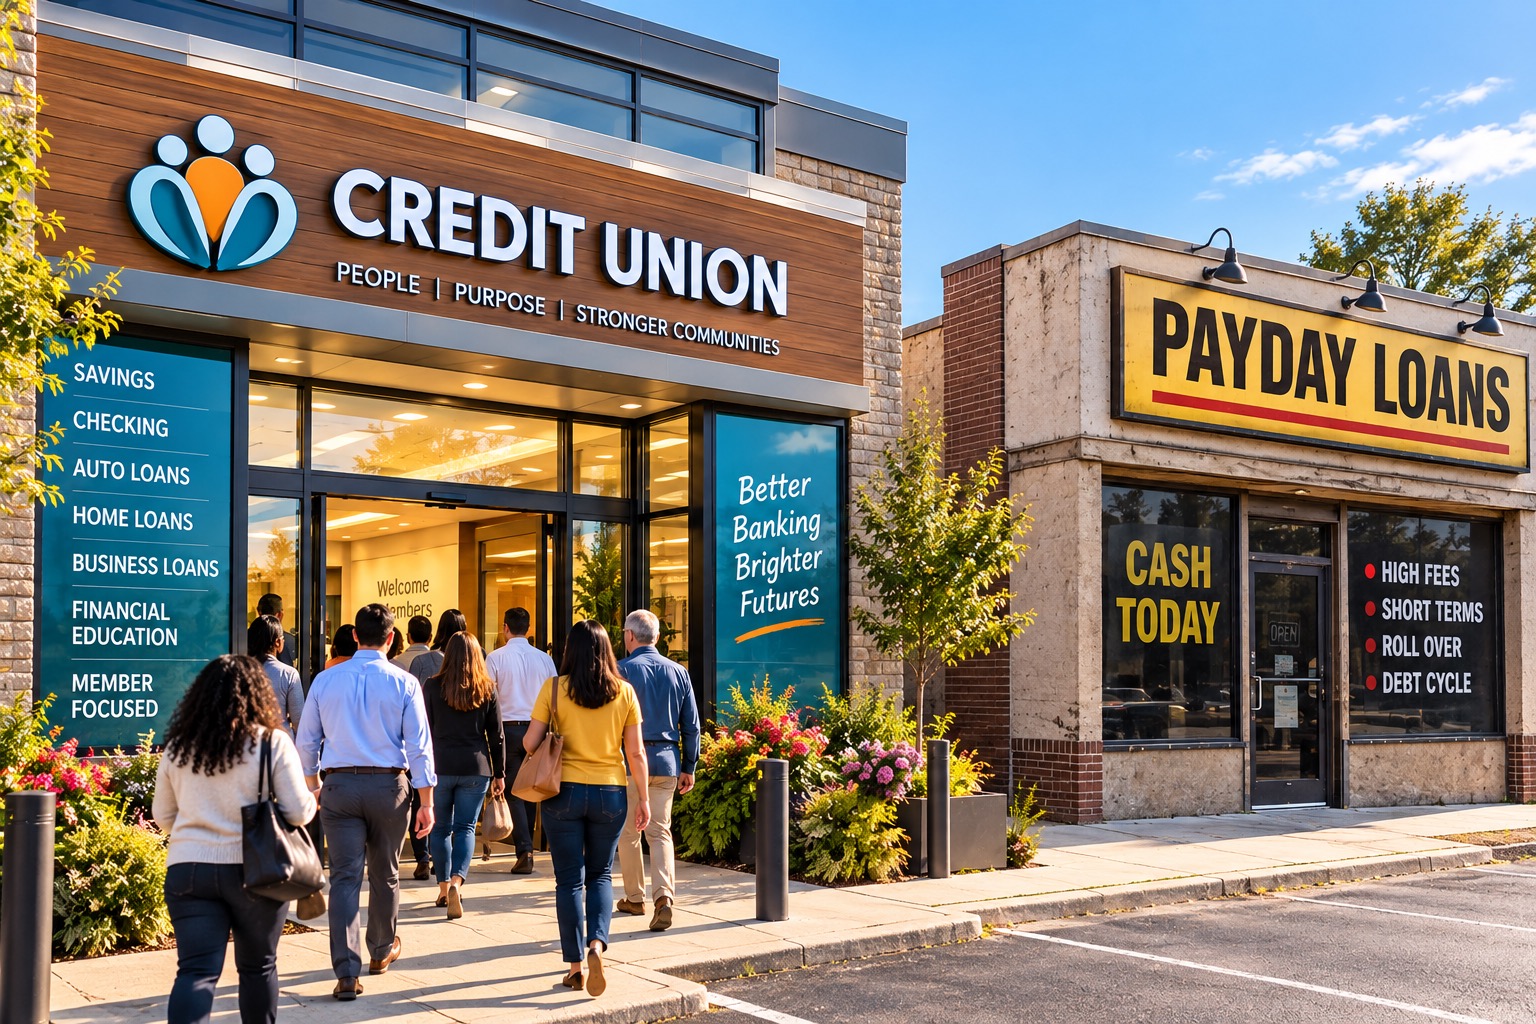
Rivermark Community Credit Union in the Portland area noticed something troubling when they dug into their overdraft data. A bunch of their members were paying high-cost cash advance services—basically getting fleeced by predatory lenders when they hit a rough patch. You know, the kind of short-term money crunch that happens to pretty much everyone at some point.
Instead of shrugging it off, Rivermark decided to step in. They’ve partnered with fintech company Salus to launch an instant microloan program specifically aimed at ALICE households. That’s Asset Limited, Income Constrained, Employed people—folks who are working but living paycheck to paycheck without much cushion.
When Your Data Tells You What Your Members Really Need
“This fits into our CDFI strategy to better serve the underserved ALICE community in our area,” says Cheryl McCarthy, Rivermark’s VP of product development and management. “We have a financial wellness department that offers financial coaching, and microloans are a natural extension of that commitment to our members’ long-term financial health.”
For context, Rivermark is a Community Development Financial Institution—a CDFI—which means they’re specifically chartered to expand financial access to underserved communities. It’s literally in their DNA to help people who traditional banks might overlook.
After shopping around for the right partner, they landed on Salus. The platform handles more than just microloans—it also offers credit risk monitoring with predictive analytics, earned wage access, and credit building through rent reporting. McCarthy liked that Salus could scale with them over time and that the platform was clearly designed with actual humans in mind. “It’s very easy to use; it’s obviously built with the member in mind,” she noted.
Getting Comfortable with Smart Risk
Here’s where it gets interesting from a strategy standpoint. Rivermark CMO David Noble says the credit union has been deliberately shifting its risk philosophy. “We are moving our risk appetite from moderate to tolerant,” Noble explains. “We want to be more risk-seeking, and microloans fit that strategy well.”
Noble’s realistic about what this means financially. This isn’t going to be a “balance sheet mover,” he says—Rivermark expects to provide about 5,000 loans in the first year. But the real value isn’t just in the dollars and cents of the loan program itself.
The Numbers Tell a Compelling Story
Rivermark looked at what happened when GFA Federal Credit Union launched a similar program with Salus, and the results are pretty eye-opening:
- Microloan borrowers took out additional loans at 2.5 times the rate of other members
- Those borrowers generated $1.65 million in additional loans
- Deposits from microloan borrowers grew 65%, including a 70% jump from millennials and 90% from Gen Z
- Members saved nearly half a million dollars compared to what they would’ve paid payday lenders and other predatory services
Translation: When you help members in a moment of need, they stick around. They trust you more. They do more business with you. It’s almost like treating people well is good for business. Wild concept, right?
“Rivermark sees what the most forward-thinking credit unions are beginning to understand: serving members in their moment of financial need is not a risk to manage away but an opportunity to build lasting relationships,” says James Chemplavil, founder and CEO of Salus. “When a CDFI like Rivermark combines its financial coaching resources with instant, affordable microloan access, it creates something no fintech can replicate. We exist to help credit unions make members for life.”
The Bigger Picture
Rivermark is a $3.2 billion credit union serving more than 180,000 members across Oregon and Southwest Washington. The microloan program launches in mid-November, and it represents something bigger than just another product offering. It’s what happens when a financial institution actually looks at member behavior, identifies a pain point, and builds a solution that serves people instead of exploiting them.
In a world where payday lenders charge triple-digit interest rates and cash advance services quietly drain people’s bank accounts, that’s not just good business. It’s the right thing to do.